At Thursday’s close in US markets, the Nasdaq wiped out roughly $2.5 trillion in market capitalization, officially sending the index into technical correction territory. A glance at the post-market heat map reveals a stark divide across the tech sector: the Big Tech titans signing the checks remained largely unperturbed, while downstream hardware and infrastructure suppliers suffered an outright collapse.
This divergence shatters a two-year industry consensus—namely, that as long as hyperscalers keep escalating compute spending, suppliers will effortlessly ride the wave. In reality, physical grid constraints have slammed the brakes on deployments, and buyers are beginning to tighten their purse strings. In this tug-of-war, the risk burden has quietly shifted down the supply chain.
The $2.5T Wipeout: Hyperscalers Drop 3%, Suppliers Plunge 14%
The trading data tells an unforgiving story. The mega-caps cutting the AI capex checks saw minimal declines: Alphabet dipped just 2.29%, Microsoft fell 3.25%, and Amazon dropped 3.55%. For trillion-dollar balance sheets, these moves represent standard market fluctuations.
Downstream suppliers, by contrast, faced a bloodbath. AMD plunged 14.83%, memory giant Micron plummeted 14.18%, server integrator Dell dropped 12.88%, and GE Vernova slipped 11.88%. Even bellwethers Nvidia and Broadcom surrendered 7.53% and 8.07%, respectively. Semiconductor equipment heavyweights Lam Research and Applied Materials both tumbled over 10%.
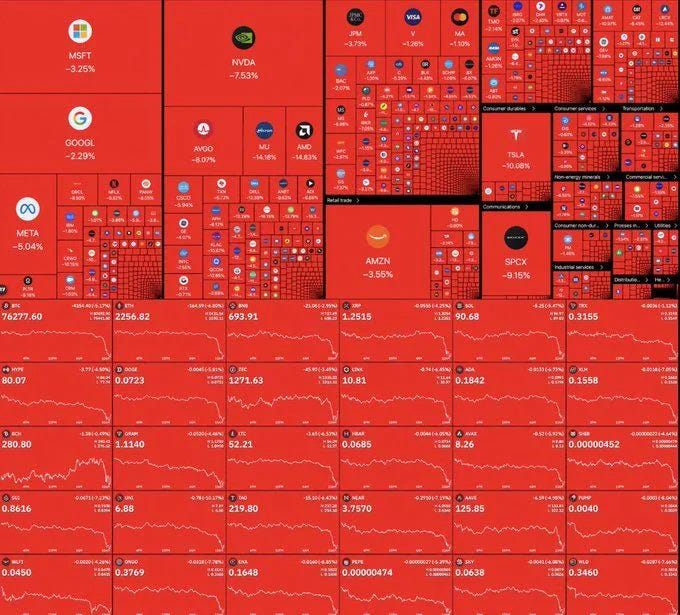 Figure: US stock market heatmap. Downstream suppliers suffered far steeper losses than hyperscale buyers. Source: finlaws.substack.com (Tomasz Dziurko).
While the shares of capital spenders held firm, pick-and-shovel suppliers saw valuations slashed across the board. This price action dismantles the assumption that buyers and sellers will rise and fall in tandem. Buyers wield superior pricing power and capital buffers, leaving hardware suppliers to absorb the brunt of the downturn alone.
Giants Can Absorb Cash Bleed; Suppliers Cannot Afford a Deceleration
Big Tech’s resilience amid the selloff stems from the sheer cash-generation power of its core franchises. Last quarter, Alphabet reported negative free cash flow of $9.1 billion, while Amazon’s trailing 12-month free cash flow stood at negative $42.4 billion, accompanied by full-year capex guidance of $220 billion.
Despite burning tens of billions in cash, the hyperscalers remain on solid footing. Google commands reliable cash flows from global search and digital advertising; Amazon leans on AWS and retail cash generation. Even if these giants defer hardware procurement by two full quarters, core operational cash flow ensures their balance sheets remain pristine.
For buyers, capital expenditure functions as a valve that can be dialed back at a moment’s notice. The moment hyperscalers tap the brakes on orders, free cash flow will swiftly pivot back into positive territory. They possess ample strategic depth to absorb investment cycle swings.
Hardware suppliers enjoy no such luxury. The premium multiples attached to Nvidia, Broadcom, Lam Research, and Applied Materials are predicated on unrelenting compound growth in gigawatt-scale data centers. Wall Street’s valuation models baked in an assumption of perpetual infrastructure acceleration. Their manufacturing capacity expansions involve staggering sunk costs. If hyperscaler order curves merely flatten, supplier earnings will promptly fall off a cliff.
Midterms Stall the Grid: 500-Megawatt Interconnections Frozen
Compute expansion has collided head-on with the physical reality of the power grid. Following Tuesday’s midterm elections, Democrats secured governorships in Texas, Georgia, and Ohio, alongside control of Congress. Crucially, these three states host the vast majority of planned gigawatt-scale computing clusters across the United States.
Newly elected local officials campaigned on clear pledges to freeze approval pipelines for mega-data centers. The underlying conflict is acute: dense clusters of computing facilities are driving up electricity rates for local residents. As household utility bills climb, voter backlash has translated directly into state-level regulatory intervention.
A single 500-megawatt data center consumes as much electricity as hundreds of thousands of standard households. Expanding high-voltage transmission lines and substation transformers takes years. The ambitious compute blueprints of Big Tech have directly intensified competition with local communities over energy allocations.
Once interconnection permits for a single 500 MW facility are frozen by local utility boards, hardware deployments grind to a halt. Construction teams cannot power up facilities on schedule, and hyperscalers will not take delivery of racks and GPUs piling up in warehouses. In a matter of weeks, physical grid bottlenecks have shattered the smoothly modeled growth trajectories of Wall Street financial models.
Servers Siphon Memory Wafers; Smartphone Shipments Hit 14-Year Low
The crowding-out effect of the AI infrastructure boom is now rippling into consumer electronics. Qualcomm tumbled 12.65% in a single session as smartphone chip revenues contracted by 26%. Data from Counterpoint Research shows quarterly global smartphone shipments dropped 20%, touching a 14-year low.
This plunge in shipments reflects more than weak consumer demand; it stems from a strategic reallocation of semiconductor manufacturing capacity. Producing High Bandwidth Memory (HBM) requires stacking multiple silicon dies—a complex packaging process with lower yields that consumes several times more wafer area than standard DRAM. Micron and SK Hynix shifted massive volumes of cutting-edge capacity to HBM, severely constricting the supply of conventional mobile DRAM and NAND flash.
Component shortages quickly drove up the bill of materials for consumer devices. To safeguard margins, handset makers were forced to hike retail prices. Consumers have refused to pay inflated prices for handsets merely marketed around AI, leaving consumer hardware channels frozen.
The very same infrastructure wave that cloud hyperscalers treat as capital investment has become a crushing cost burden for consumer hardware. Qualcomm’s steep drop and the collapse in phone volumes underscore how AI infrastructure is draining liquidity and component supply from the broader consumer ecosystem.
Passing the Bill: Hardware Valuations Reconnect with Physical Limits
With $2.5 trillion wiped off the Nasdaq, the trajectory of financial risk has come into sharp focus. Tech giants have insulated themselves behind monopolies that generate steady cash, ready to dial down capex whenever necessary to burnish their financial statements. The suppliers equipping them stand exposed on the front lines, devoid of similar maneuvering room.
As local ballots freeze grid interconnections and consumers push back against inflated prices, hardware suppliers have become the frontline breakwater absorbing the cost. Wall Street’s assumption that data centers could scale frictionlessly has been punctured by physical constraints.
While buyers retain the prerogative to slam on the brakes, suppliers have wagered everything on keeping the accelerator floored. If grid interconnections face further delays or consumer markets continue resisting price hikes, the crack in hardware order books will only widen. The valuation framework for the hardware supply chain must ultimately submit to the governing laws of energy availability and real-world demand.
Note: The original article includes a single market heatmap graphic.
References:
- finlaws.substack.com Market Analysis Weekly (Tomasz Dziurko).
- Counterpoint Research Global Smartphone Market Tracker.
- Recent quarterly earnings reports and capex guidance calls from major tech companies.