Seven Years Late and Finally Live: The Big Six Are Nowhere in Sight
On November 9, 2026, Payments Canada officially announced the operational debut of the Real-Time Rail (RTR) payment system. Originally initiated back in 2015, this national infrastructure initiative arrived seven years behind its inaugural schedule. Its activation eliminates Canada’s awkward status as the lone G7 economy without an operative 24/7 instant settlement network.
The day-one participant roster surprised industry observers. The initial cohort of eight live organizations is heavily dominated by agile fintechs—including Wealthsimple and KOHO—alongside foreign financial institutions. Notably absent from the roster was the entire domestic oligopoly: Canada’s Big Six banks, which handle the vast majority of consumer and corporate deposits.
Launching without the domestic giants sharply limits immediate consumer impact. The CEO of challenger platform KOHO candidly remarked that an RTR launch missing the Big Six resembles performance theater. Leadership at Wealthsimple echoed this reality, noting that true network effects can materialize only after all deposit-taking institutions plug into the rail.
This institutional inertia stands in sharp relief against the projected macroeconomic upside. Think-tank economic modeling indicates that day-one features alone could eliminate up to $14.5 billion in frictional costs over the coming decade. Net economic benefits are forecast to start at $16 billion, expanding to as much as $27 billion as extended functionality rolls out. Yet faced with massive societal dividends, the six incumbents commanding Canada’s retail deposits chose to sit tight on the sidelines.
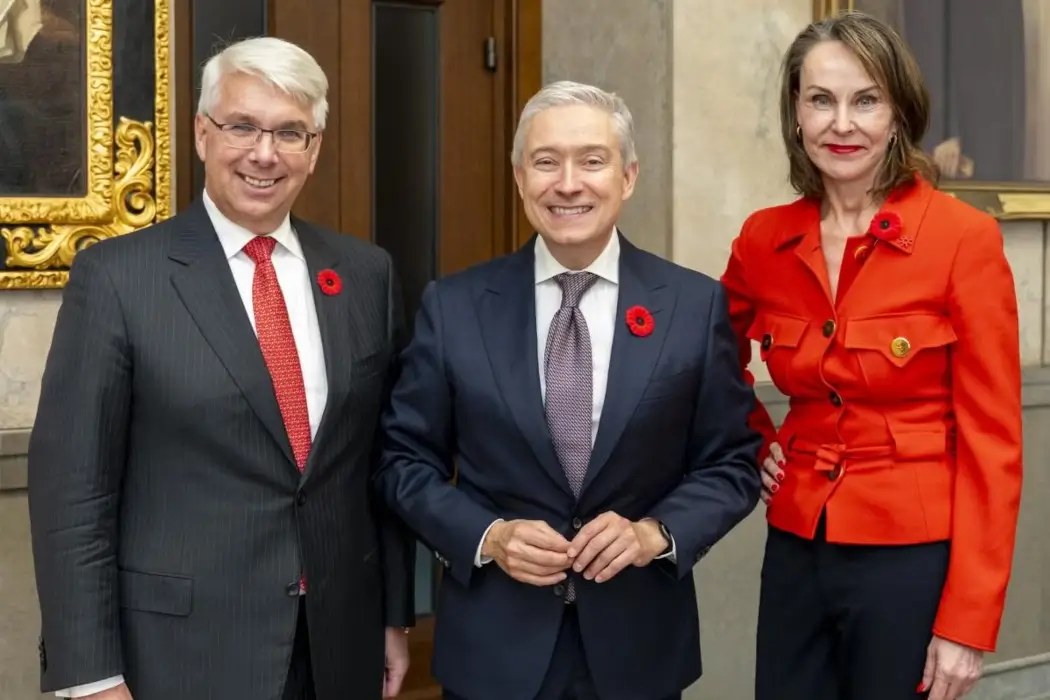 Photo: At the RTR launch event, Ron Morrow, Executive Director of Payments at the Bank of Canada; François-Philippe Champagne, Minister of Finance; and Susan Hawkins, CEO of Payments Canada. Source: BetaKit
Decades of Batch Clearing: Billions Frozen Daily in Transit
Canadian households and businesses have long endured payment workflows measured in business days rather than seconds. A standard interbank transfer initiated on Friday afternoon frequently idles until the following week. Businesses routinely stage vendor payouts two to three days in advance to meet payroll and accounts payable cycles. This glacial pace is hardcoded into clearing pipelines designed in the mid-twentieth century.
Legacy settlement relies entirely on batch-oriented architectures. Participating financial institutions aggregate daytime transaction logs into flat batch files, exchanging and reconciling ledger entries during restricted nocturnal clearing windows. Funds leaving an originator’s account often hang in transit limbo for 24 to 48 hours. This mountain of unresolved transit volume effectively supplies commercial banks with a risk-free pool of zero-cost float.
The widely adopted Interac e-Transfer system does not offer true core instant settlement. It is an application-layer messaging product laid atop proprietary networks, bounded by strict transactional transfer ceilings. Behind the scenes, its underlying interbank net settlements remain tied to legacy batch schedules. For enterprise treasury desks executing multi-million-dollar capital transfers, such patched consumer overlays are structurally inadequate.
The RTR replaces this entire topology. Operating on the contemporary ISO 20022 messaging standard, the new platform delivers continuous, year-round real-time gross settlement. Account debiting and beneficiary crediting execute concurrently in seconds with complete finality and irrevocability. By compressing transit latency to zero, the network systematically dries up the legacy float pools that institutions long monetized.
The Cost of Legacy Core Overhaul: Giants Cling to the Status Quo
Deep-seated architectural debt forms the primary roadblock for incumbent banks. Core banking engines across the Big Six still largely run on decades-old COBOL applications and centralized mainframes. These architectures were engineered around nocturnal maintenance windows dedicated to serial batch processing and interest accruals. Meeting around-the-clock, sub-second transactional concurrency demands fundamental re-engineering of foundational ledgers.
Modernizing aging core systems represents an astronomically expensive and high-risk undertaking. For an individual tier-one bank, migrating transaction modules and messaging switches is a multi-year effort with virtually zero margin for rollback. Any calculation anomaly or core outage during migration risks crushing regulatory penalties and brand erosion. For risk-averse executives, deferring the overhaul remains far safer than being the first casualty of an operational misfire.
Shifted economic incentives further erode incumbent motivation. Under traditional clearing constraints, wire transfer fees, cheque processing charges, and overdraft overdraft penalties have generated highly predictable fee income. Once zero-friction instant settlement becomes ubiquitous, fee models sustained by transaction latency collapse. Incumbent institutions prefer dragging compliance timelines to statutory deadlines rather than disrupting their own profit engine.
 Photo: The official RTR launch conference. Source: Fintech.ca
Challenger institutions, conversely, faced completely different economics. Free of legacy mainframe liabilities, cloud-native tech companies connected to RTR APIs within months. Sub-second gross settlement eliminates switching friction for retail deposits, giving young players institutional-grade clearing firepower. The new rails level the playing field—and established gatekeepers have zero incentive to accelerate that leveling.
Instant Finality Precludes Reversal: Centralized Fraud Defense Must Precede Launch
Accelerating settlement velocity radically alters fraud surfaces. Traditional multi-day batch delays provided a natural operational buffer, allowing human investigators and asynchronous risk engines time to intervene. When an account holder reported a deceptive wire, risk departments could frequently freeze transit queues prior to net settlement. On instant networks, funds transfer instantaneously and permanently.
Regulatory ambiguities regarding liability amplify these engineering hazards. Canadian banking regulations do not currently mandate that financial institutions reimburse victims of authorized push payment (APP) fraud. Once an account is drained through an instant pipeline, everyday consumers possess practically no legal recourse for fund recovery. In the United States, several regional institutions previously halted instant settlement access precisely due to unresolved liability exposure.
To prevent runaway fraud losses, Payments Canada integrated defense-in-depth directly into core topology. Canada stands as the first G7 jurisdiction to mandate an active, centralized risk mitigation engine at launch. The central transaction gateway, engineered and operated by Interac, embeds real-time payee account validation and cross-network threat telemetry directly into the settlement path.
Consumer accounts gained automated payee confirmation on day one. Before funds depart, the system authenticates the beneficiary entity name against official registration records, neutralizing impersonation scams at origin. Concurrently, the transaction engine scores payments in flight, dynamically blocking anomalies. Erecting an interconnected defense fabric before opening the rails was the necessary engineering prerequisite for instant national payments.
Legacy Forced into Upgrades: The Decisive Shift Moves to 2027
The initial onboarding of eight agile institutions is merely the prelude to industry-wide migration. Regulators structured mandatory adoption across three successive tranches, ultimately encompassing all federally regulated deposit-taking entities. Canada’s largest lender, Royal Bank of Canada (RBC), is not slated to integrate until Q2 2027. Official projections forecast the network reaching over 90% of the Canadian population within twelve months of opening.
Demand-side momentum for modern settlement is unmistakable. Industry survey metrics reveal that 60% of commercial enterprises and more than half of retail consumers actively seek relief from days-long clearing delays. Enterprises want an end to physical cheques and manual ledger reconciliations, striving to maximize working capital velocity. Market expectations have decisively outgrown clearing architectures designed over a half-century ago.
That RTR required eleven years to reach production was never fundamentally a failure of communication protocols or computer science. Instant payment rails have operated globally for years; algorithmic designs and distributed ledgers are well-proven patterns. The core bottleneck has always been structural—reconciling entrenched institutional revenue models against multi-million-dollar modernization bills. The fintech debut is simply the skirmish; the true inflection point arrives in 2027 when the Big Six are finally forced onto the track.
Reference Links:
- Payments Canada Official Announcement: Real-Time Rail Phase 1 Goes Live
- C.D. Howe Institute Research Report: Economic Dividend Evaluation for Canadian Real-Time Payments
- BetaKit Deep Dive: RTR Launches After Long Wait Without Big Six Banks
- Fintech.ca Industry Interview: How Challenger Banks View the Launch of Canada’s RTR Platform
- Hacker News Discussion (item?id=50427362)